NAEPC Webinars (See All):
Issue 49 – October, 2026
Critical Tax Implications for Estate Planning With Unmarried Couples
Peter Holstead Davies, JD, LL.M. (taxation), AEP®
SYNOPSIS: Estate planning for unmarried couples presents unique challenges and opportunities, particularly through the lens of federal taxation. This article examines those challenges and opportunities and explores areas where estate planners in all fields might wish to give special attention.
Introduction
Imagine meeting a happy couple in their mid-seventies. They have adult children in who all get along, grandchildren who seem set up for success, and a financial portfolio in excess of the current estate and gift tax exemption amount. They just celebrated their fiftieth anniversary. It turns out, though, that they were never legally married.
Whether individuals in this situation never married, or were married, divorced, and reconciled without remarrying, marital status matters significantly for federal tax purposes, including income taxation, and estate and gift taxation. A December 2, 2025, release from the U.S. Census Bureau shows “fewer than half (47%) of U.S. households in 2025 were married couples — a significant shift from 50 years earlier, when nearly two-thirds (66%) were [married couples]. Among married-couple households, the share with their own children declined over the past half-century.”[2] How are these unmarried couples taxed?
If horizontal equity in this context stands for the proposition that similarly situated taxpayers should be taxed correspondingly, how do the taxpayers living in a relationship analogous to marriage fare from a tax perspective? Should the lack of marriage result in a different tax outcome for these taxpayers, who have all the indicia of marriage, but for the technical formalities of legal marriage? Do the tools in the estate planning toolbox change as a result of marital status, and which taxpayers get the better result? The tools clearly change. Married couples have lifetime tools, such as higher § 121 exclusions[3], marital deductions for spousal gifting, and gift-splitting. They also have at-death tools, such as the marital deduction and portability. If federal tax doctrine favors economic reality and substance over form, how is this doctrine applied to unmarried couples? And what constitutes marriage for federal tax purposes? The following will examine the federal tax implications of marriage.
Marital Status
In examining taxes in the context of marriage, an overview of legal marital status may be useful.
Generally
1 USC § 7(a) states, “For the purpose of any Federal law, rule, or regulation in which marital status is a factor, an individual shall be considered married if that individual’s marriage is between 2 individuals and is valid in the State where the marriage was entered into […].”[4] For federal taxation purposes, IRC § 7703 clarifies that, “the determination of whether an individual is married shall be made as of the close of his taxable year; except that if his spouse dies during his taxable year such determination shall be made as of the time of such death […].”
The jurisprudence regarding the federal government deferring to state-based determination of marital status can be found in case law. For example, in Ankenbrandt v. Richards[5], the United States Supreme Court extended the Court’s recognition of a domestic relations exception in Barber v. Barber[6] (dealing with issues concerning divorce and alimony), to include an exception of the federal courts taking up matters concerning child custody orders. “Given the long passage of time [since Barber, a decision from 1858] without any expression of congressional dissatisfaction, we have no trouble today reaffirming the validity of the [federal domestic relations] exception as it pertains to divorce and alimony decrees and child custody orders.”[7] “The significance of state responsibilities for the definition and regulation of marriage dates to the Nation’s beginning; for ‘when the Constitution was adopted the common understanding was that the domestic relations of husband and wife […] were matters reserved to the States.”[8]
The federal deference to the states is not absolute, however. As mentioned above, federal law envisions marriage being limited to two individuals. Challenges to state and federal law concerning polygamy have been unsuccessful.[9] And as we will see below, challenges have been made successfully regarding the recognition of same-sex marriage.
The current environment regarding the laws of marriage can be summarized as this: For federal purposes, the state’s determination of whether someone is married is dispositive[10] (subject to certain restrictions, such as 1 USC § 7 limiting marriage to two individuals, thus excluding polygamy). States must recognize same-sex marriage.[11] And a state/district may but need not, recognize common law marriage.
Same-Sex Marriage
As for the recognition of same-sex marriage, this jurisprudence is new. The issue, from a federal tax perspective, is significant in that individuals who were living in a relationship analogous to marriage, and who wanted to formally marry but were prohibited from doing so, were unable to take advantage of certain tax attributes that were available to married couples, such as the marital deduction for lifetime gifting and for estate taxes. As shown below, the right to marriage for same-sex couples came somewhat piecemeal.
The Supreme Court, in United States v. Windsor[12], took the issue of same-sex marriage and the estate tax marital deduction head-on. At the time, in 2009, the Defense of Marriage Act defined “marriage” to be limited to “a legal union between one man and one woman as husband and wife, and the word ‘spouse’ refers only to a person of the opposite sex who is a husband or a wife.”[13] While the Defense of Marriage Act did not prohibit states from allowing same-sex marriages or civil unions, it had sweeping implications at the federal level.[14] A same-sex couple, Edith Windsor and Thea Spyer, were residents of New York but lawfully married in Canada. A few years later, Spyer died, leaving her estate to Windsor. The IRS disallowed Spyer’s estate from claiming the marital deduction under IRC 2056(a), resulting in an estate tax owed. The tax was paid and Windsor sued for a refund. At issue was the constitutionality of the Defense of Marriage Act’s definition of “spouse,” and it stating marriage is between a man and a woman. In holding in favor of Windsor, the court wrote, “The federal statute is invalid, for no legitimate purpose overcomes the purpose and effect to disparage and to injure those whom the State, by its marriage laws, sought to protect in personhood and dignity.”[15]
Following Windsor, the Internal Revenue Service issued Rev. Rul. 2013-17, which served to move the Service toward more gender-neutral phrasing and a post-Windsor interpretation of “spouse” and “husband and wife” to include same-sex spouses in light of the Supreme Court’s ruling. Though largely administrative housekeeping following Windsor, Rev. Rul. 2013-17 was another step toward today’s jurisprudence and statutory interpretation of marriage.
In Obergefell v. Hodges, the Supreme Court noted that the petitioners seeking the right to marry were not seeking to “demean the revered idea and reality of marriage,” but that “the petitioners seek it for themselves because of their respect — and need — for its privileges and responsibilities.”[16] Essentially, the ruling in Obergefell advanced same-sex marriage as a nationwide right under the Fourteenth Amendment.
Common-Law Marriage
The implications of marital status for federal tax purposes are significant, so it is critical to correctly determine one’s marital status. In addition to same-sex marriage, some states allow common-law marriage. This is an instance of substance over form prevailing in the context of defining marriage.
The Internal Revenue Service states, “A common-law marriage is a union of two people created by agreement followed by cohabitation that is legally recognized by a state. Common-law marriages have three basic features: (1) A present agreement to be married, (2) cohabitation, and (3) public representation of marriage.”[17]
Regarding common-law marriage, each state may determine whether to allow common-law marriage. For example, the District of Columbia does;[18] Virginia does not.[19] In the District of Columbia, common-law marriage is not established by statute, but by case law. One might also argue that common-law marriage exists except in those instances where it is prohibited by the state. In Hoage v. Murch Bros. Const. Co., the court took exactly that position as it related to common-law marriage in the District of Columbia. The issue was whether the individual was married to a deceased Murch Brothers Construction Company employee who left spousal survivor benefits. The court traced the roots of common-law marriage jurisprudence back to England and traced it forward to the year of the decision in 1931. The Hoage court noted that English law eventually prohibited common-law marriage by act of Parliament, but that the act of Parliament “was never adopted in any of the states of the United States.”[20]
Marriage requires two things: (i) a license, and (ii) solemnization.[21] In a state that does not recognize common law marriage, there is a bright line rule for becoming married. While there have been instances where people entered into subsequent marriages believing erroneously that their prior marriage had been legally terminated, thereby rendering the subsequent marriage void,[22] it is generally clear whether one is married. It becomes less clear in states that recognize common-law marriage due to the lack of a bright line licensure/solemnization formality.
It should be noted that common-law marriage issues arise elsewhere. As Justice Kennedy observed in the Windsor opinion, “[I]n establishing income-based criteria for Social Security benefits, Congress decided that although state law would determine in general who qualifies as an applicant’s spouse, common-law marriages should also be recognized, regardless of any particular State’s view on these relationships.”[23] (Emphasis added.)
Registered Domestic Partnerships
A registered domestic partnership is a state-based recognition of a relationship status that falls just shy of marriage for state (and therefore federal) purposes.[24] However, a registered domestic partnership may create certain significant state rights similar to those who are married, such as the authority to be a visitor of one’s partner who is in the hospital,[25] in certain instances the ability to file a joint tax return at the state level (though not at the federal level),[26] an ability to inherit under the state’s probate system,[27] and, where applicable, granting community property rights.[28] Additional rights may include standing to file a wrongful death action and to be a statutory beneficiary,[29] and the ability to take leave from work to care for the domestic partner.[30]
Although a registered domestic partnership does not rise to the level of federal recognition of marriage for the registered domestic partners, it is worth examining the rights of these taxpayers because other rights, including state income taxation, may be impacted.
Lifetime Taxation Issues
Having hopefully settled what is, and is not, a legal marriage for federal taxation purposes, now let us explore some of the taxation issues.
Gifting Issues — The Marital Deduction, Inadvertent Gifts, and Consequences
Internal Revenue Code § 2501 imposes a tax “for each calendar year on the transfer of property by gift during such calendar year by any individual or nonresident.”[31] § 2502 imposes a graduated rate of tax, which is tied statutorily to the estate tax rates, beginning at 18% and topping out at 40%. Gifts more than the annual gift tax exclusion amount, the inflation-adjusted exclusion amount in 2026 is $19,000, trigger the filing requirement of Form 709, United States Gift (and Generation-Skipping Transfer) Tax Return, per § 2503. The donor elects on Form 709 to use the donor’s exemption amount or, if none remaining, pay the gift tax.
For married couples, § 2523 provides a marital deduction from the gift tax. “Where a donor transfers during the calendar year by gift an interest in property to a donee who at the time of the gift is the donor’s spouse, there shall be allowed as a deduction […].”[32] It is important to note that the statute contemplates a deduction only for gifts made during the marriage. If, for example, an unmarried donor makes a gift to his or her partner, and then later marries in that same taxable year, the marital deduction as to that pre-marriage gift is disallowed because the donor and donee were not married at the time of the gift, as § 2523 requires.
Note that the deduction is disallowed where the spouse of the donor is not a U.S. citizen.[33] Although the deduction is disallowed, the annual gift tax exclusion amount of $10,000 (adjusted for inflation) is replaced by an annual gift tax exclusion amount of $100,000 (likewise adjusted for inflation). In 2026 numbers, this means that a donor may give the noncitizen spouse gifts not to exceed $194,000 annually without incurring gift tax. Any gift in excess of the annual gift tax exclusion amount, as modified for the non-citizen spouse, would be treated as a taxable gift.
§ 2523(b) likewise establishes “terminable interest” rules regarding the disallowance of the deduction on gifts to spouses “where, on the lapse of time, on the occurrence of an event or contingency, or on the failure of an event or contingency to occur, such interest transferred to the spouse will terminate or fail.” Legislative exceptions to the terminable interest rules may be available, such as § 2523(f), allowing the marital deduction in instances of qualified terminable interest property.
For unmarried couples, the uninformed taxpayer may fall into the trap of making a taxable gift to the taxpayer’s partner. In instances of gifts in excess of the annual gift tax exclusion amount, such as adding the partner to the title of the taxpayer’s principal residence, the donor taxpayer is required to file a Form 709 and either pay the gift tax or use a portion of his or her remaining lifetime exemption amount as to the gift made in excess of the annual gift tax exclusion.
In the instance of unmarried couples intentionally making taxable gifts to each other, the donor is typically required to pay the gift tax (assuming the donor does not have any exemption amount remaining or in the unlikely scenario the donor does not wish to use the remaining exemption). If the parties agree prior to the gift that the donee will pay the gift tax, Rev. Rul. 75-72 provides a formula for the parties to follow in calculating the gift tax. Rev. Rul. 75-72 provides an answer to the circular calculation that results from the payment of the gift tax by the donee reducing the amount of the gift. In instances where the parties do not have an agreement in place prior to the gift, the issue of reducing the value of the gift is moot and the donee pays the tax without resorting to the Rev. Rul. 75-72 formula.
The statute of limitations period for the Internal Revenue Service to contest Form 709 is three years.[34] There are certain exceptions to the three-year statute of limitations period, such as a filing a false return and willful tax evasion. But applicable to the well-intentioned but ill-informed unmarried taxpayers is § 6501(c)(3): No return. “In the case of failure to file a return, the tax may be assessed, or a proceeding in court for the collection of such tax may be begun without assessment, at any time.” Even if a Form 709 is filed, the gift must be adequately disclosed.[35] There are failure to file penalties (5% of the amount of tax owed, per month, not exceeding 25% in the aggregate)[36] and failure to pay penalties (0.5% per month, not exceeding 25% in the aggregate).[37] Accuracy and fraud related penalties, while unlikely to be relevant here, may also apply.[38] In addition to the possible penalties, there is also interest on underpayments (or non-payments, as the case may be) of the gift tax.[39] The interest rate is the applicable federal short-term rate plus three percentage points.[40]
In the context of unmarried couples where one has added the other to the title of the principal residence, the addition of the partner, to the extent it exceeds the annual gift tax exclusion amount, is a taxable gift. If the partners do not know how to file a gift tax return, the statute of limitations clock never starts. If the taxable gift is later discovered, from the point of the gift forward there could be failure to file penalties, failure to pay penalties, interest on the tax, and the gift tax itself. The problem compounds if the parties did not keep good records and do not know what the value of the gift was. Even if the parties easily can establish what the assessed tax value was for real estate tax purposes, which is likely to be insufficient for valuation purposes in the context of the gift tax. Treas. Reg. § 25-2512-1 addresses valuation in this context, and “its value at the date of the gift shall be considered the amount of the gift. The value of the property is the price at which such property would change hands between a willing buyer and a willing seller, neither being under any compulsion to buy or sell, and both having reasonable knowledge of relevant facts.”
Gift Splitting
Internal Revenue Code § 2513, “Gift by husband or wife to third party,” allows married couples (including same-sex couples in the post-Windsor world) to split gifts, provided certain criteria are met. When splitting gifts, the gift is treated as having been made equally between the spouses although the asset gifted may originate from only one. As with qualifying for the marital deduction for spousal transfers, the couple must be married at the time of the gift to gift split,[41] consent of both parties is required[42] and both spouses must be U.S. citizens or residents.[43]
Gift splitting also impacts generation-skipping transfers. For split gifts, spouses can use both of their generation-skipping transfer exemptions. In instances of disparate wealth between the two spouses, this can be an effective technique to utilize the generation-skipping transfer exemption of the spouse with the smaller estate.
A low-hanging fruit technique for high net-worth couples is broad gifting up to the annual gift tax exclusion amount. For example, in 2026, the annual gift tax exclusion amount is $19,000. Married couples may gift split and gift twice that amount to, say, each of their children. And their children’s spouses. And their grandchildren. And so on. With enough recipients, this is an easy and effective way to transfer wealth from one taxpayer to another with effectively no gift tax implications whatsoever. The unmarried couple is not as fortunate, particularly where one person has the majority of the wealth. In that instance, the wealthier member of the couple is limited to the annual gift tax exclusion amount and can only give half of what the married couple can with no gift tax consequences.
Suppose the wealthier of the unmarried taxpayers wishes to make an annual gift tax exclusion amount transfer to a nephew. The donor could give $19,000 to the nephew in 2026; the donor pays no tax, the nephew pays no tax, and no Form 709 need be filed. Could the donor give an additional $19,000 to the donor’s partner, with the expectation that the partner then in turn gift that second $19,000 to the nephew? Yes, but the IRS would likely view this as a transfer from the donor to the nephew, regardless of the transfer to the donor’s partner. Under the step-transaction doctrine, tax law, and the courts specifically, favor substance-over-form and economic reality. If the facts showed that the donor’s partner never viewed the receipt of the $19,000 as belonging to them, and that the partner was expected to forward the money to the nephew, the court would collapse the transaction into its economic reality, the second $19,000 was in fact an additional transfer from the donor to the nephew.
But setting that significant hurdle aside, the landscape is still unfavorable to the unmarried couple, especially if the wealthy partner is looking to broaden annual gifting to transfer wealth. Transfers made to the other partner would not avoid gift tax consequences because an unmarried couple is not eligible for the marital deduction under § 2523. Accordingly, gifts from the wealthier partner that exceed the annual exclusion constitute taxable gifts. With high net-worth taxpayers living in a relationship analogous to marriage, the removal of gift-splitting from the toolbox is significant.
Jointly Owned Property
Jointly owned property takes one of three forms: a tenancy in common, a joint tenancy, and, in the cases of married individuals, a tenancy by the entirety.[44] (These tenancies can be impacted by state law in which certain states recognize community property titling. Community property is outside the scope of this topic.) Not all states recognize a tenancy by the entirety, which is at its essence a legal fiction that an asset owned as a tenancy by the entirety is owned by the marriage. A tenancy by the entirety is available only to married couples, and it gives the asset unique creditor protection.[45] Jointly owned property, particularly by unmarried taxpayers, can present challenges.
Going back to the unmarried couple, assume that they decide to open a joint bank account to manage their day-to-day household operating expenses. They open a joint bank account with rights of survivorship and contribute $20,000. Already, they may be disadvantaged. Because they cannot own the account as tenants by the entirety with the right of survivorship, the asset is not given creditor protection that states recognizing a tenancy by the entirety allow. But what about the tax consequences? Has either made a gift to the other? This answer is: It depends.
In this context, the gift is complete when the donor ceases to have dominion and control over the asset. If the donor “reserves any power over its disposition, the gift may be wholly incomplete, or may be partially complete and partially incomplete, depending upon all facts in the particular case.”[46] In the joint bank account example, above, there is no gift until the other withdraws the money. If one opens the joint account and funds it with $20,000 in year one, there is no completed gift until the other withdraws the money. If the non-contributing party withdraws the entire balance in year two, the gift takes place in year two. The tax consequences are that one of them has made a gift in year two of $20,000, $19,000 of which is covered by the annual gift tax exclusion, and $1,000 of which is taxable, not covered by the exclusion.
Things get more complicated when they both contribute to the account. In instances of unmarried couples sharing a joint bank account, it would not be unusual to have both partners making contributions and withdrawals. Assume that in year one, in addition to contribution of $20,000 partner 1, partner 2 also makes a $80,000 contribution. In year two, if partner 2 withdraws $20,000, there is no gift, assuming the withdrawal can be traced to partner 2’s $80,000 deposit. But suppose many years go by, with many more deposits and withdrawals. And the account is earning interest. With unmarried couples, something as simple as a jointly owned bank account for household operating expenses can get terribly complicated, especially if the couple is made to reconstruct which partner is responsible for which deposits and withdrawals. Although Treas. Reg. § 25.2511-1(h) provides clear guidance in the instance of the simple year one to year two example (“there is a gift to [her] when [she] draws upon the account for [her] own benefit, to the extent of the amount drawn without any obligation to account for a part of the proceeds to [him]”), this becomes less clear as the facts get more complicated, such as the allocation of interest earned on the joint account. At some point, it is as though red paint has been mixed with blue paint, and it cannot be logistically undone. It is unlikely that the owners of the joint account have been filing gift tax returns, thus never starting the statute of limitations for the Internal Revenue Service.
The practical solution is to keep separate accounts. But for unmarried couples, that might not be palatable. Of course, there are many instances when other people may wish to have joint bank accounts, such as parents sending their children to college. Actors Ben Affleck and Matt Damon shared a bank account in Boston to cover travel expenses to auditions early in their careers.[47] If a joint account is to be had, maintain good records, including deposits and the depositor, withdrawals and the one making the withdrawals. In instances of the account earning income, keep track of the individual to whom the interest is being allocated. If the parties are aware of a withdrawal from the funds of the other, file Form 709 to start the clock on a challenge from the IRS. Realistically, though, it seems unlikely that any of these is going to be practical for most people co-owning a bank account. But for high net-worth taxpayers or any others who are particularly susceptible to scrutiny by the IRS, diligent recordkeeping is called for.
§ 121 Exclusion
Internal Revenue Code § 121 provides for an exclusion of gain from the sale of a principal residence provided the taxpayer meets both an ownership requirement and a use requirement. For unmarried taxpayers, the amount of gain excluded from gross income shall not exceed $250,000.[48] For married taxpayers, the exclusion shall not exceed $500,000.[49]
To qualify for the exclusion, the taxpayer — in this example, a single taxpayer owning the principal residence alone — must meet two prongs during the five-year period ending on the date of sale[50]: an ownership prong, and a use prong. Under the ownership prong, the taxpayer must have owned the principal residence for at least two of the last five years before sale. Under the use prong, the taxpayer must have used the principal residence as such for at least two of the last five years. Provided the taxpayer meets both prongs, $250,000 of gain will be excluded from the taxpayer’s gross income.
Things become more generous for married taxpayers. § 121 provides that, “In the case of a husband and wife [which includes same-sex couples] who make a joint return for the taxable year of the sale or exchange of the property, [the exclusion amount is $500,000 rather than $250,000] if: (i) either spouse meets the ownership requirement […], (ii) both spouses meet the use requirements […], and (iii) neither spouse is ineligible [as a result of having taken advantage of a prior § 121 exclusion within two years immediately prior to the subject transaction].”[51] Although both spouses must meet the use requirement and neither must have used a § 121 exclusion within the prior two years, only one spouse needs to meet the ownership in order for the married taxpayers to double their exclusion amount.
Compare this result to the unmarried couple. If only one owns the principal residence, but both meet the use requirement, and the owner has not used a § 121 exclusion within the prior two years, the gain exclusion will be capped at $250,000, half the exclusion amount available to the similarly situated, though married, taxpayers.
Unmarried taxpayers can co-own property. The tax consequences follow title. Said differently, if the unmarried taxpayers purchase their principal residence as 50/50 owners, whether as tenants in common or as joint tenants with the right of survivorship, each will be deemed to own fifty percent of the property for tax purposes. When they sell their principal residence, the § 121 analysis is applied to their respective use, ownership, gain, and, if applicable, exclusion of gain from their gross income.
In instances where one of the taxpayers owned the principal residence prior to the relationship with the other taxpayer, things can become inadvertently complicated. For a married taxpayer, adding the spouse to the title of the primary residence so that they own the property as, for example, tenants by the entirety with the right of survivorship, is a gift but the marital deduction applies.[52] As joint owners holding title as tenants by the entirety, the married couple gets special creditor protection and, due to the legislative generosity in § 121(b)(2)(A)(i), where only one spouse need meet the ownership prong, the spouses will have the $500,000 exclusion amount, assuming the other requirements have been met. For the similarly situated, though unmarried, taxpayers, if one adds the other to the title of the principal residence, a gift results, and likely a gift tax as to the value of the gift less the annual gift exclusion amount.
ERISA Plans
One area that may be more of an administrative burden on married taxpayers is in the context of the Employee Retirement Income Security Act of 1974 (or “ERISA”). Unmarried taxpayers are free to list whomever they wish as the beneficiary of their ERISA-governed retirement account (most private employer pensions and most 401(k) plans). Married taxpayers must list the spouse unless the spouse gives written consent to allow otherwise.[53]
State law can revoke some death benefits in the event of a divorce[54], but ERISA plans are subject to federal law, which can preempt state law. For unmarried couples, a breakup has no operation of law, and the owners of the assets would be well advised to review their beneficiary designations.
Breaking Up
If happy partners living in a relationship analogous to marriage have tax consequences for adding each other to assets, such as their primary residence, so, too, do unhappy couples that break up.
For married couples, § 1041 addresses gain and loss issues in two circumstances: First, there is no gain or loss recognized between spouses.[55] This includes transfers to trusts that are for the benefit of the spouse.[56] Second, there is no gain or loss recognized between former spouses, “but only if the transfer is incident to divorce.”[57] There are special rules for nonresident alien spouses and instances in trust transfers where liability exceeds basis[58], but generally there is no gain or loss between spouses during the marriage or after the marriage provided the transfers are incident to divorce.
For unmarried couples, there is no relief under § 1041. If the unmarried couple terminates the relationship and assets are divided because of the split, gain or loss must be recognized. The breakup, in a sense, becomes a taxable event. In practice, it seems unlikely that the taxpayers going through the breakup are contemplating the tax implications and are reporting any gain or loss resulting from transfers between the unmarried couples. But for high net-worth taxpayers and those who are otherwise subject to increased scrutiny from the Internal Revenue Service, transfers resulting from the end of a relationship can be an unexpected tax vulnerability.
Gain and loss aside, the unmarried couple splitting up may have unanticipated gift tax issues, too. Consider again the couple who jointly own a house. When one partner added the other to the title, there would be gift tax consequences because of the transaction, assuming the value in question exceeded the annual gift tax exclusion amount. Similarly, but in reverse, going from a joint tenancy to a fee simple estate as a result of removing one of the partners from the title could also have gift tax consequences. Compare this to a married couple who, for whatever reason, want to add or remove a spouse from the title to the real estate. These taxpayers have no federal gift tax consequences from the transaction due to § 2523, and no gain or loss consequences from the transaction due to § 1041. Married couples change title for various reasons. In states that do not allow a tenancy by the entirety, a couple may want to remove one of the spouses from the title of the home if, say, one of the spouses practices medicine in a high-risk field and does not want to expose the marital home to claims of that spouse’s creditors in the event of a malpractice claim.[59] Or, in states that do allow a tenancy by the entirety, one of the spouses may wish to add the other to the title such that the spouses own the asset as tenants by the entirety and gain the unique creditor protection that that tenancy offers. For unmarried couples, there is a tax event at every turn in these types of transactions.
At-Death Taxation Issues
Jointly Owned Property
Recalling the joint bank account example, above, how will the account be treated for estate tax purposes?
For married individuals, § 2040(b) provides an absolute 50/50 rule for property held as joint tenants with the right of survivorship or as tenants by the entirety. Regardless of what either spouse contributed to the account, the result is that only 50% of the jointly owned account is included in the first-to-die spouse’s gross estate for federal estate tax purposes, even if there is incontrovertible evidence that the contributions were other than 50/50; it is an absolute rule.
For an unmarried couple (or any other owners of a joint account with the right of survivorship), the entire balance is included in the decedent’s gross estate, “except such part thereof as may be shown to have originally belonged to such other person and never to have been received or acquired by latter from the decedent for less than an adequate and full consideration in money or money’s worth.”[60] The rule can be expressed formulaically, with the numerator being the amount contributed by the decedent over the total amount. In the example above, he contributed $20,000 of the $100,000 account balance, giving 0.2. That 0.2 is then multiplied by the value of the joint property, here, $100,000, assuming no change in value, for an inclusion of $20,000 in his gross estate for federal estate tax purposes.
Again, married, and unmarried co-owners are treated differently. The married couple gets the absolute 50/50 rule, regardless of the spouses’ respective contributions to the account. For the unmarried co-owners, the entire value of the jointly owned asset is included in the value of the gross estate, with a burden on the personal representative of the deceased account holder to prove otherwise.
Portability
The Tax Relief, Unemployment Insurance Reauthorization, and Job Creation Act of 2010 brought about portability for decedents dying on or after January 1, 2011. This allowed estates of such decedents the ability to elect, through a timely filed Form 706, the ability to transfer the first-to-die spouse’s unused exclusion amount to the surviving spouse. Portability was made permanent through the American Taxpayer Relief Act of 2012.
Although registered domestic partnerships grant the partners some inheritance rights, the creation of a registered domestic partnership is not sufficient to grant portability. The couple need be actually married — whether a result of common-law marriage or the state-level statutory formalities, typically licensure and solemnization. The Internal Revenue Code Section granting portability, § 2010(c), does so through the lens of a “surviving spouse.” A spouse must legally be a spouse but may include same-sex couples. However, portability is unavailable if the surviving spouse is a nonresident who is not a U.S. citizen, unless allowed under any applicable treaty.[61]
Because unmarried couples are not spouses, portability is unavailable to them. Married taxpayers, however, can capture the first-to-die spouse’s unused exclusion amount for the benefit of the surviving spouse. This can be helpful on several fronts. First, for married taxpayers who have assets approaching the federal estate tax threshold for a single taxpayer, claiming portability when the first spouse dies is akin to purchasing tax insurance — the one-time premium is the cost of paying the professional to complete and file the Form 706, but the surviving taxpayer is now very unlikely to need to worry about estate or gift tax exposure. Second, it is conceptually easier for some taxpayers to understand that, in a sense, they can double their exemption amount. It is more nuanced than that; the deceased spouse’s unused exclusion (or “DSUE”) amount is a snapshot in time when the first spouse dies, and the exemption amount could (and likely will be) different when the second spouse dies. But it makes explaining the concept a little easier. Third, it can simplify drafting. If the taxpayers are positioned to rely on portability, their estate planning documents can, where appropriate, be simplified, as estate tax concerns can be resolved outside of their estate planning documents.
Married taxpayers are further favored in the context of remarriage after the death of the first spouse. This is particularly true of high net-worth taxpayers and portability. Suppose husband and wife are both high net-worth individuals. The wife dies. The husband, as the executor of his wife’s estate, files Form 706, elects’ portability, and gets his deceased wife’s DSUE amount. At this point in time, the husband has his remaining exemption amount plus his wife’s DSUE. If husband makes a taxable gift, he uses the DSUE amount first, prior to using his own basic exclusion amount.[62] This allows for a strategy where the husband can fully exhaust the wife’s DSUE amount by lifetime gifting. If he then remarries and his new wife predeceases him, her executor may file Form 706, elect portability, and port to the husband the second wife’s DSUE amount. Prior to the second wife’s death, the husband would be well-advised to consider using all his first wife’s DSUE. (Note that remarriage itself does not cause the husband in this example to lose the DSUE from the first wife. However, if he remarries and his second wife dies, the second wife would be the husband’s last deceased spouse, and any unused DSUE from the first wife ceases to be available. The used DSUE from the first wife, though, remains considered. See Treas. Reg. § 25.2505-2 and Treas. Reg. § 20.2010-3.) Of course, unmarried couples do not have this advantage.
Marital Deduction
§ 2056 grants a marital deduction for the first-to-die spouse’s gross estate for federal estate tax purposes. The language of the statute, as with the marital deduction for spousal lifetime gifts, anticipates the deduction being available only for married couples. The deduction shall “be determined by deducting from the value of the gross estate an amount equal to the value of any interest in property which passes or has passed from the decedent to his surviving spouse […].”[63] For outright transfers of assets to the surviving spouse at the decedent’s death, this results in an offsetting deduction from the decedent’s estate as to the value of those asset. While this might reduce the estate tax liability to zero, it is a deferral of the estate tax because the assets will be taxed when the surviving spouse dies. Of course, there are nuances in non-outright spousal transfers, such as the terminable interest rule. But the point is that married couples have an extraordinary tool to mitigate the estate tax.
Returning to the concept of estate tax deferral when assets pass to a surviving spouse, in instances where the surviving spouse is not a U.S. citizen, special rules apply. § 2056(d)(1) disallows the marital deduction. If a noncitizen spouse receives an asset, outright, from the estate of the first-to-die spouse, there is no marital deduction. However, § 2056(d)(2) allows a deduction in instances where the transfer to the noncitizen spouse is in trust, called a Qualified Domestic Trust, or QDOT. Estate tax applies to distributions to the surviving spouse.[64] Exceptions are made for income distributions and distributions made on account of hardship.[65] And, in keeping with the concept of deferral instead of avoidance, estate tax applies on the remaining trust assets upon the surviving spouse’s death.[66]
As seen below, the unmarried couple will have concerns that may not befall the married couple who has access to § 2056. Because the unmarried couple lacks the marital deduction, it may be that the entire value of the estate passing to the surviving partner is included in the first to die’s estate for federal estate tax purposes. Where the married couple gets the benefit of estate tax deferral via the marital deduction, the unmarried couple encounters it when the first partner dies. In the instance of a taxable estate, this could mean that the surviving partner is left with considerably less if the first-to-die partner’s estate needs to spend resources to satisfy a federal estate tax liability.
Retirement Plans
Another instance of married couples receiving preferential treatment is in the context of retirement plans, specifically at the death of one of the spouses. Following the SECURE Act and its subsequent refinements, the rules for retirement plans at the employee’s death got complicated. One observer wrote, “The rules have gotten much more complicated than before — while the potential rewards for complying with them shrank.”[67] Without getting into the weeds, the gist is this for married couples: The surviving spouse has certain options that the unmarried partner does not. For example, the surviving spouse may have a spousal rollover option, impacting required beginning dates for mandatory distributions. The surviving partner, however, may be stuck with the ten-year rule, accelerating the income tax burden that may otherwise be stretched out for married people. Depending on the surviving partner’s age, the surviving partner may qualify as an eligible designated beneficiary if the surviving partner is not more than ten years younger than the decedent.[68] In that event, the surviving partner’s circumstances are in closer approximation to the surviving spouse, but even so, the surviving spouse still has options the surviving partner does not, such as the rollover option.
Planning Techniques for Unmarried Taxpayers
Basis Considerations
Assets in a decedent’s gross estate get a step-up (or step-down, if applicable) in basis to fair market value as of the decedent’s death per § 1014, unless the alternate valuation date is elected. For taxpayers not exceeding the exemption amount, the estate planning pivot may be from estate and gift tax mitigation to basis considerations.
For the unmarried couple, the basis planning may look like this: He creates and funds a revocable living trust. He gives his partner a general power of appointment over the trust assets. If he dies, the assets will be included in his gross estate for federal estate tax purposes, but the assets will also get a step-up in basis. If his partner dies before he does, the assets will be included in her estate under § 2041 and will get a step-up in basis. If both partners are living, she may likewise create and fund a grantor trust, giving her partner a general power of appointment over the trust assets. If she dies first, the assets will be included in her estate per § 2033 and will get a step-up in basis. If he dies first, the assets will be included in his estate under § 2041 and will get a step-up in basis.
This plan is not without problems. First, under the Reciprocal Trust Doctrine, the above-described example may be so mirror-image that the parties are in the same position after the trusts were created and funded that they were pre-establishment and funding.[69] This can be mitigated by creating the trusts on different dates, preferably in different years. The partners can select separate trustees. The remainder beneficiaries of the respective trusts can be different, with different distribution standards. The general powers of appointment can be different. The more differences the partners’ trusts have, the more protection they have from the Reciprocal Trust Doctrine.
Another issue is that if the partners grant each other a general power of appointment, there is heightened creditor exposure. The general powers of appointment — the ability to appoint assets to the partner, the partner’s creditors, the partner’s estate, or the creditors of the partner’s estate — open the door to loss of assets.
A final problem arises in those instances where the unmarried taxpayers have a taxable estate. There, the battle becomes estate and gift tax mitigation versus basis planning (and income tax mitigation). For high net-worth taxpayers, particularly those unmarried taxpayers who do not have the benefit of the estate tax deferral under § 2056, estate freeze techniques and charitable giving may be of use. Although the S in SLAT stands for “Spousal,” a typical Spousal Lifetime Access Trust plan would work well for the high net-worth, unmarried taxpayers. The risks for the unmarried taxpayers are the same as married couples using SLATs — the Reciprocal Trust Doctrine, premature death, and breakups. Likewise, the attention is on mitigating the estate tax, so the basis issues remain (e.g., carryover basis into the SLAT, and no step-up).
Other Estate Freeze Options
Available to married and unmarried taxpayers alike are “estate freeze” options, those tools designed to approximate a snapshot in time of the taxpayer’s wealth and have future appreciation outside of the taxpayer’s estate, or, in some circumstances, to defer the growth within the taxpayer’s estate.
In the instance of unmarried taxpayers, particularly if one is wealthy and the other is not, estate freeze techniques may be an appropriate way to transfer some of the wealth from one partner to the other. For example, the wealthier partner may create an intentionally defective grantor trust for the benefit of the taxpayer’s partner, sell to the trust assets that are likely to appreciate, and take from the trust a promissory note in exchange.
If unmarried taxpayers are charitably minded, charitable trusts may be solutions to consider in mitigating both estate and gift tax and income tax. In the instance of age and wealth disparity, the older, wealthier unmarried partner may wish to create a charitable lead trust, getting a lifetime tax advantage for the wealthier partner, and providing some liquidity for the younger, less wealthy partner at the end of the term.
Although all these options are not uniquely positioned to help unmarried taxpayers, they may need to be relied upon more heavily as other tools, such as portability, are unavailable.
Gift Tax Versus Estate Tax
Basis considerations aside, high net-worth couples, married or otherwise, may wish to consider making taxable gifts over bequests due to the gift tax being exclusive and the estate tax being inclusive. Simply put, the donor will make a taxable gift and pay the gift tax because of that transfer. If the transfer is made in the form of a bequest, the decedent’s estate will be liable not only for the estate tax but will also pay tax on the money used to pay the gift tax, because the money to pay the gift tax was likewise in the decedent’s estate.
But it is unlikely that basis considerations will be set aside. The estate plan is not constructed in a vacuum. Depending on the assets in the portfolio, weight will need to be given to basis step-up under § 1014 (and therefore estate inclusion) versus carryover basis under § 1015, with future growth happening in the hands of the recipient, or at least out of the hands of the donor.
Liquidity Concerns
Unmarried couples may not find the relief of the estate tax marital deduction offered in
§ 2056 when the first partner dies. Instead, in instances of high net-worth taxpayers, there will be an estate tax owed when the first partner dies. This will be more impactful on the surviving partner than it would be on a surviving spouse. The unmarried couple may need to be more mindful to liquidity needs when the first partner dies to pay the estate tax and to continue to provide for the surviving partner. The solution may be found in life insurance, particularly if the first-to-die partner’s assets were illiquid, such as a closely held business or real estate investments. An irrevocable life insurance trust may be considered and structured to provide that liquidity and prevent the life insurance proceeds from entering the gross estate of the decedent.
Inconsistencies and Policy Reform
“From their beginning to their most recent page, the annals of human history reveal the transcendent importance of marriage. […] [M]arriage is essential to our most profound hopes and aspirations.”[70]
The courts[71] and tax code seem to favor marriage. The tools in the toolbox for married couples exceed those for unmarried couples. Unmarried couples must reckon with the reality of their circumstances from a tax perspective. Though the courts tout the doctrines of economic reality and substance over form, the doctrines’ reach does not, and likely will not, extend to unmarried couples, at least not within the context of defining marriage. From an administrative perspective, the line is helpfully clear, one is either married or is not.
While there is inconsistent treatment of unmarried couples in situations nearly identical to those of married couples, the tax consequences of blurring the line of marital status seem sprawling. If anything, perhaps registered domestic partnerships could be given marital recognition for federal tax purposes. That would seem consistent with the federal government recognizing common-law marriages if allowable by the individual, respective states.
Rather than trying to shoehorn couples into a legal status that, for whatever reason, they have chosen to forego[72], policy reform may be better focused on simplifying the rules that taxpayers, married or not, must abide by.
Conclusion
Unmarried couples, particularly those who fall into the high net-worth category, must be given unique attention to ensure that all planning opportunities are met, especially considering so many estate planning tools available for married couples being unavailable. Whether or not the legal blessing of “married” overcomes the substance-over-form doctrine is debatable (married individuals need not even cohabitate); but it seems probable that it will be the status quo for the foreseeable future.
Already a system exists where the states can determine what constitutes marriage, and the federal tax system mostly respects the states’ determinations. Those unmarried couples who seek the same tax laws as the married couples may be wise to make a state-level appeal. At the federal level, to give to all taxpayers, regardless of relationship status, the special rules, and exceptions available for married couples would serve to upend many policy considerations baked into the tax code. Not recognizing gain or loss, for example, transfers between spouses may make sense; marriage can be viewed as an economic partnership. If the marriage requirement evaporated in this § 1041 example, taxpayers would be able to avoid tax on countless transactions. Although it might be unfair to some couples, and raise some substance over form objections, granting everyone the same tax rights as married couples would unravel significant portions of the tax code, an unraveling too considerable to seriously consider.
[1] JD, LL.M. (taxation), AEP®. The author thanks GULC Prof. Cara Koss for her guidance and support on this project. Any errors are the authors.
The author used AI, hardcover legal encyclopedias, LexisNexis, Google searches, lecture slides, and so on to research this topic.
[2] Census Bureau Press Release Number CB25-TPS.78, https://www.census.gov/newsroom/press-releases/2025/families-and-living-arrangements.html. The press release also cited that, “In 1975, more than half (54%) of married-couple households include their own children under age 18; by 2025, that share had declined to 37%.” Id. Last accessed on February 16, 2026.
[3] Unless noted otherwise, all code section references are to the Internal Revenue Code, Title 26 of the United States Code.
[4] 1 U.S.C. § 7(b) clarifies that “State” also includes the District of Columbia, the Commonwealth of Puerto Rico, etc.
[5] Ankenbrandt v. Richards, 504 U.S. 689 (1992).
[6] Barber v. Barber, 62 U.S. 582 (1858).
[7] Ankenbrandt, 504 U.S. at 703.
[8] Windsor, citing Ohio ex rel. Popovici v. Agler, 280 U.S. 379 (1930).
[9] E.g., Reynolds v. United States, 98 U.S. 145 (1878).
[10] United States v. Windsor, 570 U.S. 744 (2013).
[11] Obergefell v. Hodges, 576 U.S. 644 (2015).
[12] United States v. Windsor, 570 U.S. 744 (2013).
[13] Then 1 U.S.C. § 7.
[14] Windsor, 570 U.S. at 752. “The enactment’s comprehensive definition of marriage for purposes of all federal statutes and other regulations or directives covered by its terms, however, does control over 1,000 federal laws in which marital or spousal status is addressed as a matter of federal law.”
[15] Windsor, 570 U.S. at 775.
[16] Obergefell, 576 U.S. at 657, emphasis added.
[17] Rev. Rul. 2013-17.
[18] Cleary v. Cleary, 318 A.3d 536 (D.C. App. 2024). “The District is part of a shrinking minority of jurisdictions that recognize common law marriages at all; just nine states and the District still recognize common law marriages.” Citing Hogsett v. Neale, 478 P.3d 713 (Colo. 2021) (en banc), which lists Colorado, Iowa, Kansas, Montana, New Hampshire, Oklahoma, Rhode Island, Utah, and Texas as the nine states recognizing common law marriage.
[19] Michie’s Jurisprudence (2025 ed.), Marriage, § 8. “Common-law marriages are void in both Virginia […], if celebrated there.” See also the cases cited therein.
[20] Hoage v. Murch Bros. Const. Co., 50 F.2d 983 (D.C. Ct. App., 1931).
[21] E.g., Va. Code Ann. § 20-13.
[22] E.g., Va. Code Ann. § 20-38.1. See also, Michie’s Jurisprudence (2025 ed.), Marriage, § 6. “However, a void marriage, in Virginia, is a mere nullity […].”
[23] Windsor at 765, citing 42 U.S.C. § 1382c(d)(2).
[24] In California, for example, this is done statutorily, defining domestic partners as, “[T]wo adults who have chosen to share one another’s lives in an intimate and committed relationship of mutual caring.” Cal. Fam. Code § 297(a).
[25] In Washington, D.C., for example, one may file a domestic partnership declaration with the mayor, thus giving the partners the ability to visit the hospitalized partner. D.C. Code § 32-704.
[26] D.C. Code § 47-1805.01(f).
[27] D.C. Code § 19-302.
[28] Cal. Fam. Code § 297.5.
[29] D.C. Code § 16-2701(a) and (b), respectively.
[30] D.C. Code § 705(a).
[31] § 2501(a)(1). Some exceptions, not relevant here, follow in the statute.
[32] Emphasis added.
[33] 26 U.S.C. § 2523(i).
[34] 26 U.S.C. § 6501.
[35] 26 C.F.R. § 301.6501(c)-1.
[36] 26 U.S.C. § 6651(a)(1).
[37] 26 U.S.C. § 6651(a)(2).
[38] 26 U.S.C. § 6662; § 6663
[39] 26 U.S.C. § 6601.
[40] 26 U.S.C § 6621.
[41] 26 U.S.C § 2513(a)(1).
[42] 26 U.S.C. § 2513(a)(2). Treas. Reg. § 25.2513-2 addresses the manner and time of signifying consent.
[43] Treas. Reg. § 25.2513-1(b)(2).
[44] Coparcenary is abolished by statute in Washington, D.C., via D.C. Code § 42.517. Though not abolished statutorily in Virginia in the same manners as in Washington, D.C., coparcenary in Virginia is practically abolished because of heirs inheriting via intestacy taking title as tenants in common. “Formerly joint tenancy was much favored, but for more than a century the courts have laid hold of every available expression to construe estates given to a plurality of tenants as tenancies in common.” A Virginia Title Examiners’ Manual (6th ed.), § 42-1(b), citing Gardner v. Gardner, 152 Va. 677, 682 (1929).
[45] See, for example, Va. Code § 55.1-136.
[46] Treas. Reg. § 25.2511-2(b).
[47] Conan O’Brien interview with Matt Damon, https://www.youtube.com/watch?v=UZ1kCEGjYX0 at 13:24; last accessed March 12, 2026.
[48] 26 U.S.C. § 121(b)(1).
[49] 26 U.S.C. § 121(b)(2).
[50] 26 U.S.C. § 121(a). In addition to sales, the § 121 exclusion can also apply in instances of qualifying exchanges.
[51] 26 U.S.C. § 121(b)(2). “Special rules for joint returns.” Emphasis added.
[52] 26 U.S.C. § 2523.
[53] 29 U.S.C. § 1055.
[54] For example, Va. Code Ann. § 20-111.1.
[55] § 1041(a)(1). This can be particularly useful for spouses who have highly appreciated, low basis assets. For example, if the wife has low basis assets and the husband is expected to die first, the wife can transfer these assets to the husband during their lifetimes. Husband takes a carryover basis in the assets, and there is no recognition of gain on the transfer, per § 1041. When the husband later dies, the assets get a step up in basis allowing his beneficiary, presumably his wife, to diversify her holdings with a fresh basis at fair market value as of her husband’s date of death (or the alternate valuation date, if applicable).
[56] 26 U.S.C. § 1041(a).
[57] 26 U.S.C. § 1041(a)(2).
[58] 26 U.S.C. § 1041(d) and (e).
[59] States not recognizing a tenancy by the entirety may nevertheless have a homestead exemption, though it may be limited to the primary residence. Not all states recognize homestead exemptions.
[60] 26 U.S.C. § 2040(a).
[61] 26 C.F.R. § 20.2010-3(e).
[62] 26 C.F.R. § 25.2505-2(b).
[63] 26 U.S.C. § 2056(a). Emphasis added.
[64] 26 U.S.C. § 2056A(b)(1)(A).
[65] 26 U.S.C. § 2056A(b)(3)(A) and (B), respectively.
[66] 26 U.S.C. § 2056A(b)(1)(B).
[67] Natalie Choate, Estate Planning for Retirement Benefits 2025-3 (Sept. 2025), Part 2, Sec. 1. For more on this topic, see Retirement Benefits, (8th Ed.), by Natalie Choate, as updated and supplemented by the aforementioned Sept. 2025 publication.
[68] § 401(a)(9)(E)(ii)(V).
[69] United States v. Grace, 395 U.S. 316 (1969).
[70] Obergefell, 576 U.S. at 656-57.
[71] “The public policy of the state is to uphold the validity of the marriage status as for the best interest of society […].” Michie’s Jurisprudence of Virginia & West Virginia, (2025 ed.), Marriage, § 6.
[72] Consider a situation where individuals wish to be together but do not want to be responsible for each other’s debts, as in the case of the Necessaries Doctrine. Or where one may qualify for public assistance, but for the spouse’s financial resources. Or perhaps someone experienced a nasty divorce and did not want to risk another protracted legal battle. The reasons to marry (or not) are as varied and nuanced as the people making the decision.
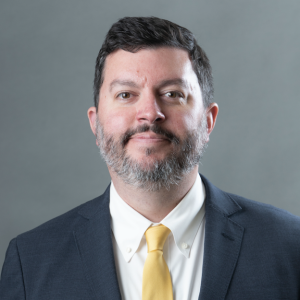 BIO: Peter Holstead Davies is a trust and estates attorney, practicing at Davies & Davies in his hometown of Lynchburg, Virginia. He serves on the Virginia State Bar’s Board of Governors for the Trusts and Estates Section as its chair, the Virginia Bar Association’s Wills, Trusts and Estates Council and Legislative Affairs Committee, the Boyd-Graves Conference, and is a past president of the Lynchburg Estate Planning Council and the Lynchburg Bar Association.